U.S. 30% Renewable Tax Credit Expires July 4; Transferability Market Survives
The 'One Big Beautiful Bill' reform repealed Inflation Reduction Act incentives but left intact the sale of tax credits to third parties, a mechanism that underpins project financing.
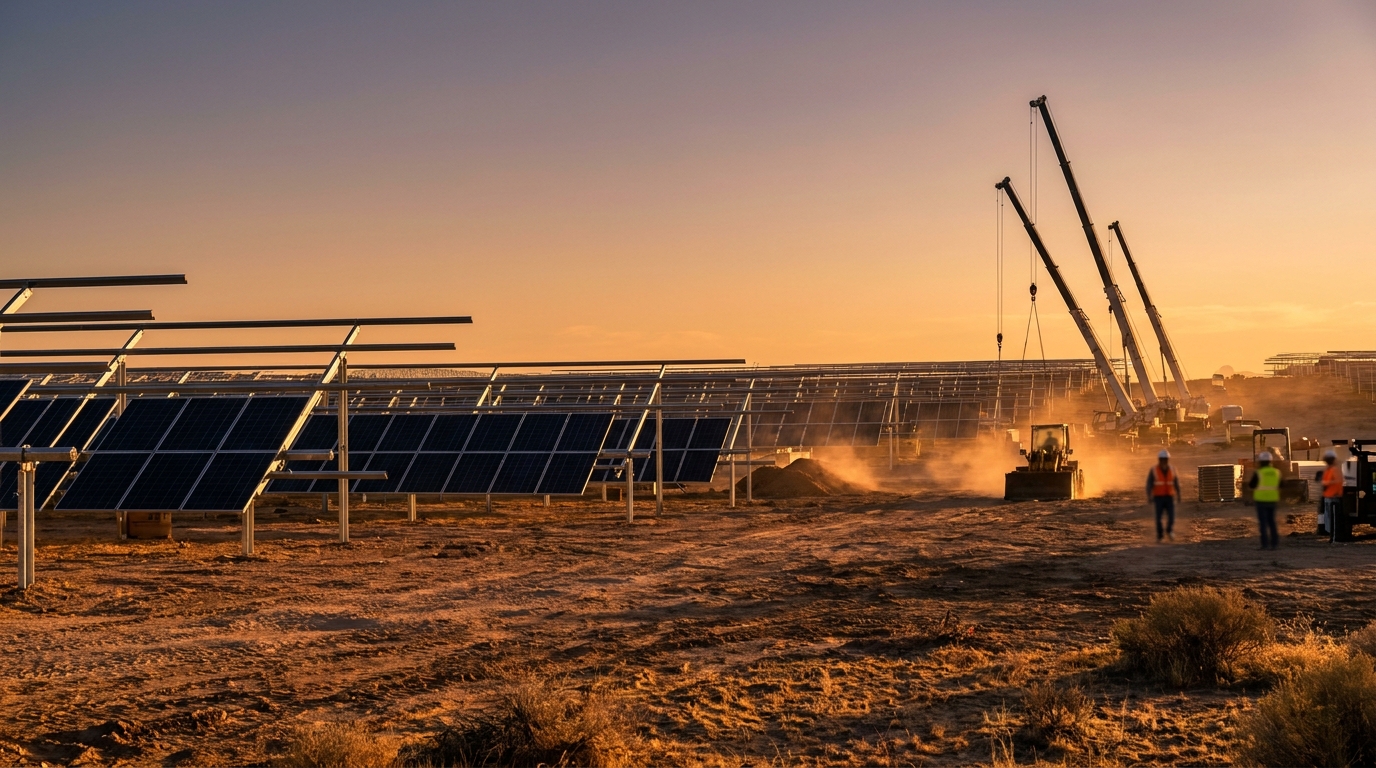
This July 4, 2026 marks the deadline for U.S. solar and wind developers to begin construction and preserve the at-least-30% tax credit granted by the Inflation Reduction Act (IRA). The 'One Big Beautiful Bill' tax reform (OBBBA), signed on July 4, 2025, repealed large segments of the IRA but left credit transferability fully intact, a mechanism that sustains liquidity across the sector.
The OBBBA ended IRA incentives for new clean energy projects. According to an analysis cited by Canary Media, the United States will build less than half the renewable capacity projected between 2025 and 2035 under the original incentive scenario, which could have mobilized up to $1.2 trillion. Wood Mackenzie estimates, per the same source, that 92 gigawatts (GW) of projects, equivalent to $121 billion in investment, are at risk due to changes in permitting policy. With fewer projects competing for components and financing in the U.S., Latin American markets (Mexico, Brazil, and Chile) face more favorable supply conditions for their own renewable developments.
Despite the repeal, transferability under Section 6418 of the U.S. tax code, which allows developers to sell credits to third parties with tax liabilities, "remained intact" in the OBBBA, according to Thomson Reuters Institute. Credits under Sections 45X, 48E, and 45Y remain transferable through 2029 and beyond, while clean fuel credits (Section 45Z) were expressly extended through that year. Electricity demand from artificial intelligence data centers adds an unexpected demand floor: the U.S. Department of Energy projects they will consume 12% of all national electricity by 2028, making large technology operators structural buyers of renewable energy, with or without the tax credit.
Projects that break ground before July 4 have a four-year window to reach completion. Those that miss the deadline can still qualify if the plant enters operation before December 31, 2027. The indicator to watch: power purchase agreements (PPAs) announced by data center operators in the third quarter of 2026.
This article was drafted with artificial intelligence assistance from verified sources and reviewed by a human editor before publication.
Sources
Related stories
This article was drafted with AI assistance from verified sources and reviewed by a human editor before publication.